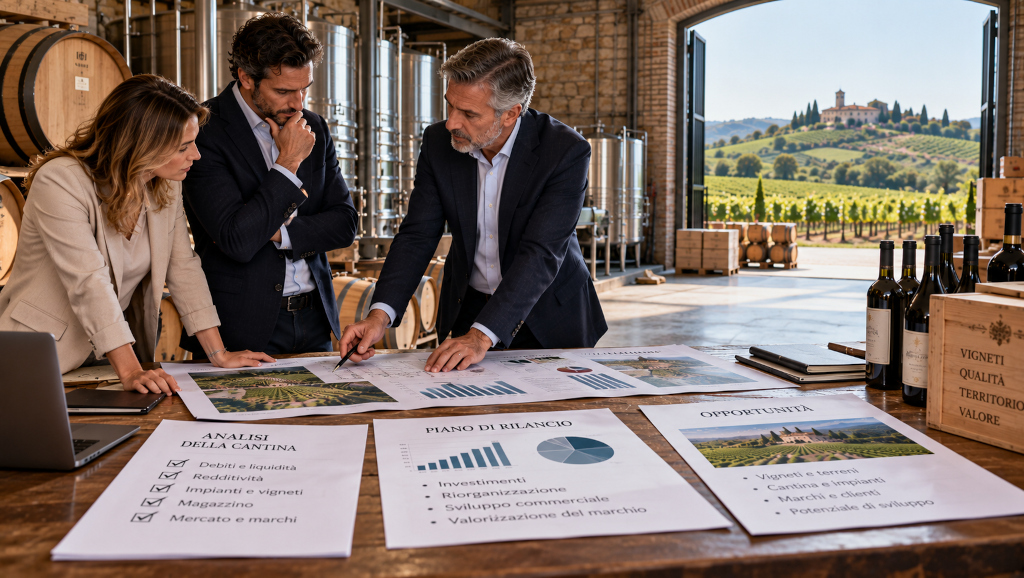
Rising production costs, pressure on margins, commercial difficulties, high inventories, and liquidity problems can put even wineries with quality vineyards, modern facilities, and well-known brands in difficulty.
Not all of these companies are destined to close. Some possess industrial, agricultural, and commercial assets that could be enhanced through new management, targeted investments, and a more effective marketing strategy.
For wine groups, industrial investors, and specialized operators, acquiring a struggling winery can mean entering a strategic territory, increasing production capacity, or acquiring a brand at attractive terms.
But a low purchase price does not guarantee a good investment.
1. Understand why the cellar is in trouble
Before evaluating an acquisition, it is necessary to identify the real causes of the crisis.
The most frequent situations concern:
The fundamental distinction is between a temporary crisis, a management crisis, and a structural crisis.
A winery with good products, reliable customers, and efficient facilities, but with an unbalanced financial structure, can offer very different recovery opportunities than a company that systematically sells below cost and has lost competitiveness.
2. What assets might make the acquisition attractive?
Vineyards and landed property
Surface area, DOC and DOCG designations, soil quality, age of vineyards, productivity, and water availability can represent important assets even when commercial activity is struggling.
Cellar and production facilities
A modern facility, with available winemaking and bottling capacity, can allow an industrial group to increase production without building a new plant.
Brands and commercial relations
A recognized brand, a network of distributors, or a consolidated presence in foreign markets can have significant value, provided they are supported by actual sales and verifiable margins.
The investor must therefore distinguish the value of individual assets from the value of the going concern. Significant real estate assets do not automatically mean the business is profitable.
3. The five crucial checks before investing
|
Area |
What to check |
|
Debt and liquidity |
Bank exposures, suppliers, taxes, contributions, guarantees and deadlines |
|
Profitability |
Margins by product, sales channel and market |
|
Plants and vineyards |
Maintenance status, productivity, required investments and authorizations |
|
Warehouse |
Quantity, quality, recoverable value and sales times |
|
Market and brands |
Active customers, contracts, distribution, reputation and business potential |
These checks must be complemented by a legal, tax, technical, and environmental analysis, with particular attention to any crisis or insolvency procedures.
A crucial factor is the structure of the transaction. Buying shares, a business, or individual assets entails different consequences in terms of liabilities, business continuity, contracts, personnel, and authorizations.
The choice must be made with competent professionals before making binding commitments.
4. The purchase price is only part of the investment
A common mistake is to value a struggling winery solely based on the discount obtained compared to the value requested by the property.
Let's consider a purely illustrative example.
Simulation of an acquisition with industrial relaunch
|
Acquisition price |
€2,000,000 |
|
Investments in plants |
€400,000 |
|
Working capital requirements |
€500,000 |
|
Reorganization and business development |
€300,000 |
|
Estimated total commitment |
€3,200,000 |
Hypothetical amounts, not related to a real company. Any assumed debts, taxes, financial charges, transaction costs, and contingencies are excluded.
In this example, the price represents only 62.5% of the initially estimated total effort.
The investor must therefore determine not only how much it will cost to acquire the winery, but above all how much capital will be needed to restore it to sustainable profitability.
5. When can relaunching really work?
A winery turnaround project has a greater chance of success when concrete industrial and commercial conditions exist.
Among these:
For example, a producer already present on international markets could acquire a winery with good vineyards and limited distribution, promoting its production through its own sales network.
In other cases, the relaunch may require a review of the wine portfolio, a reduction in less profitable products, or a reorganization of production.
However, not all wineries are recoverable. If operating losses are structural, the facilities require excessive investment, or the market fails to absorb products at profitable prices, even a seemingly profitable acquisition can become costly.
6. The industrial plan must precede the final offer
Before completing the acquisition, it is advisable to prepare a business plan lasting at least three years, preferably five years, with verifiable objectives.
The plan should include the forecast of production volumes, the evolution of revenues, expected margins, investments, financial needs and cash flows.
It is important to develop at least three scenarios: favorable, realistic, and prudent.
The sustainability of the operation must be assessed even in the event of a slower-than-expected commercial recovery, given the timescales inherent in the wine sector, from vineyard management to wine maturation and marketing.
7. FORBUS: from identifying the opportunity to relaunching
Acquiring a struggling winery requires skills that go beyond simple brokerage.
It's important to understand the industry, evaluate assets, analyze the company's numbers, identify critical issues, and build a credible business plan.
FORBUS supports investors, winemaking groups, and entrepreneurs in the acquisition, development, and relaunch of wineries, through a multidisciplinary team with economic, financial, production, commercial, and strategic expertise.
Support may include preliminary investment analysis, assessment of industrial potential, coordination of specialist assessments, negotiation, and definition of the post-acquisition development plan.
The goal is not simply to buy a winery at a reasonable price, but to acquire a business that can generate value over time.
Want to consider buying a struggling winery?
A complex business situation can hide interesting industrial opportunities, but only an in-depth analysis allows us to distinguish a recoverable investment from an excessive risk.
FORBUS is available for confidential discussions with industrial investors, wine groups, family offices, and entrepreneurs interested in acquisitions and relaunch projects in the Italian wine sector.
Talk to FORBUS about an acquisition project.
18/11/2026
17/11/2026

14/11/2026
13/11/2026